Medicare guidance
Medicare Special Enrollment Periods
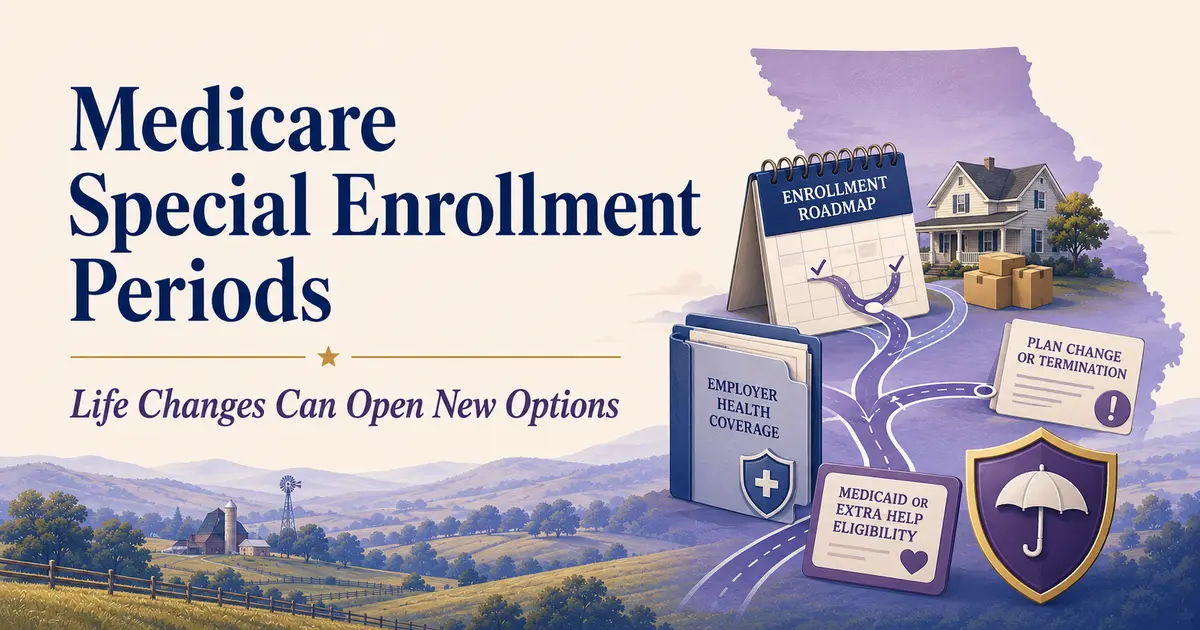
Certain changes in employment, residence, plan availability, Medicaid or other coverage can open a limited opportunity to enroll in Medicare or change private Medicare coverage. The event, permitted action and deadline must all match.
“Special Enrollment Period” Can Mean Different Things
Parts A and B after active employment coverage
If you delayed Part B because you or your spouse had qualifying group coverage based on current employment, a Part B SEP may be available while that coverage continues and generally for eight months after the employment or group coverage ends. Use the Part B SEP forms guide and the retiring-after-65 timeline.
Medicare Advantage and Part D changes
A qualifying event may permit specific plan actions for a limited time—for example, moving outside a plan’s service area, losing eligible coverage, a plan ending or certain changes involving Medicaid or Extra Help.
Medigap rights
An SEP for a Medicare Advantage or drug-plan election does not automatically create Medigap acceptance. Review separate Medigap guaranteed-issue rights and state-specific protections before leaving existing coverage.
Annual or Initial enrollment
If no qualifying event applies, another window may. Compare the Annual Enrollment Period, Medicare Advantage Open Enrollment and Initial Enrollment Period.
Situations That May Create a Medicare SEP
| Situation | Coverage question | Best next guide |
|---|---|---|
| Leaving a job or losing employer group coverage after 65 | Do you need Part B, and how will employer coverage end dates coordinate with it? | Retiring after 65 and CMS-40B/CMS-L564 forms |
| Moving to a new address | Will you leave a Medicare Advantage or Part D service area, or gain new plan choices? | Moving with Medicare in Missouri or Illinois |
| A Medicare Advantage or drug plan ends, reduces its service area or ends its Medicare contract | What replacement coverage and election rights are available? | What happens when a Medicare Advantage plan is ending? |
| Gaining, losing or changing Medicaid or Extra Help eligibility | Do eligibility changes permit a plan change or affect D-SNP enrollment? | D-SNP enrollment periods and what happens when Medicaid or D-SNP eligibility ends |
| Other exceptional conditions | Does a current Medicare rule create a specific election opportunity? | Use Medicare’s official SEP list and confirm the permitted action and deadline before changing coverage. |
A Life Change Does Not Permit Every Possible Change
Each SEP is tied to a defined event. It may allow only certain elections, and the window may begin before or after the event. Do not assume that one SEP lets you change every kind of Medicare coverage.
Likewise, returning to Original Medicare after an eligible Medicare Advantage election does not itself guarantee acceptance into a Medicare Supplement. Confirm Medigap underwriting and any guaranteed-issue protection before ending existing coverage.
Part B SEP After Working Past 65
The working-aged Part B SEP generally applies when you delayed Part B while covered by a group health plan based on your or your spouse’s current employment. The enrollment period generally continues while that qualifying coverage is active and for eight months after the employment or coverage ends, whichever occurs first.
- COBRA does not extend the eight-month Part B clock. Use the COBRA and Medicare guide.
- Retiree coverage is not current-employment coverage. Coordinate dates before the active employer plan ends.
- Employer size can affect payer order. Review the Medicare 20-employee rule.
- HSA contributions require separate planning. See the Medicare and HSA timeline.
Five Details to Confirm
- The qualifying event: identify the exact employment, move, plan, Medicaid, Extra Help or other event.
- The coverage involved: Parts A and B, Medicare Advantage, Part D and Medigap are governed by different rules.
- The window: document when the SEP begins and ends; do not rely on a generic “60-day” assumption.
- The permitted action: confirm exactly which enrollment, disenrollment or plan change the SEP allows.
- The effective date and consequences: avoid gaps and understand what happens to existing coverage, prescriptions and provider access.
Medicare SEP FAQ
How long is a Medicare Special Enrollment Period?
It depends on the qualifying event and coverage type. Some windows begin before an event; others continue for a defined period after it. Confirm the applicable Medicare rule rather than assuming every SEP lasts the same number of days.
Does losing employer coverage let me sign up for Part B?
It may when the coverage was based on current employment and the other Part B SEP requirements are met. The eight-month Part B window is different from Medicare Advantage and Part D election periods.
Does moving create a Medicare SEP?
A move can create a plan SEP when it changes your service area or plan options. A temporary trip is not the same as a permanent change of residence.
Can a SEP guarantee a Medicare Supplement?
Not necessarily. Medigap has separate open-enrollment, underwriting and guaranteed-issue rules.
Independent Medicare guidance
Match the Event, Deadline and Coverage Change
Thompson Medicare Brokerage can help Missouri and Illinois beneficiaries organize the plan choices represented by the brokerage and identify the official questions to confirm before an election.
Thompson Medicare Brokerage is not connected with or endorsed by the U.S. government or the federal Medicare program. This page is general educational information, not a determination that any person qualifies for a Special Enrollment Period. Current Medicare rules and individual facts control.